Services


Sectors
Insights
COMMERCIALIZATION
Insights



Follow Us
What should US and European companies know about bookkeeping in India?
Why bookkeeping and accounting compliance in India differ from the US and Europe
How India's financial year and statutory audit requirements affect foreign companies
What are the key accounting requirements for foreign companies operating in India?
What are the key bookkeeping challenges foreign companies face in India?
How does India's tax and regulatory framework affect accounting operations?
What bookkeeping obligations apply to different India entry structures?
How can foreign companies establish an effective bookkeeping and accounting system in India?
Should foreign companies outsource bookkeeping in India or build an in-house finance team?
What records and compliance activities should foreign companies manage in India?
How Tecnova supports bookkeeping and accounting compliance for foreign companies in India
India is now one of the largest destinations for foreign investment. Total FDI inflows reached USD 94.5 billion in FY- 2025-26, the highest annual figure on record, according to recent data.
Most companies that set up in India plan the market strategy carefully. The surprises tend to come later, in the back office. India's financial year runs April to March. Every company is audited, regardless of size. Electronic books must be backed up daily on servers in India. Tax is withheld and deposited monthly, on payments most US and European companies would never withhold on.
None of this is difficult once it is designed in from day one. It becomes expensive when it is discovered at the first audit. This guide sets out what works differently in India and how to build a bookkeeping process that satisfies Indian regulators and your group reporting at the same time.
Key takeaways
• Your entity structure (subsidiary, branch or liaison office) determines your bookkeeping obligations.
• India's statutory and tax year runs April to March. Calendar-year groups usually run two closes.
• Every Indian company needs a statutory audit. There is no small-company exemption.
• Electronic books must stay accessible in India, with a daily backup on servers located in India.
• Most new subsidiaries report under Indian GAAP, not IFRS, so plan a GAAP bridge for consolidation.
• GST and with holding tax (TDS) run on monthly cycles and must be captured at transaction level.

Foreign companies typically operate in India through one of three structures. Each carries different bookkeeping obligations.
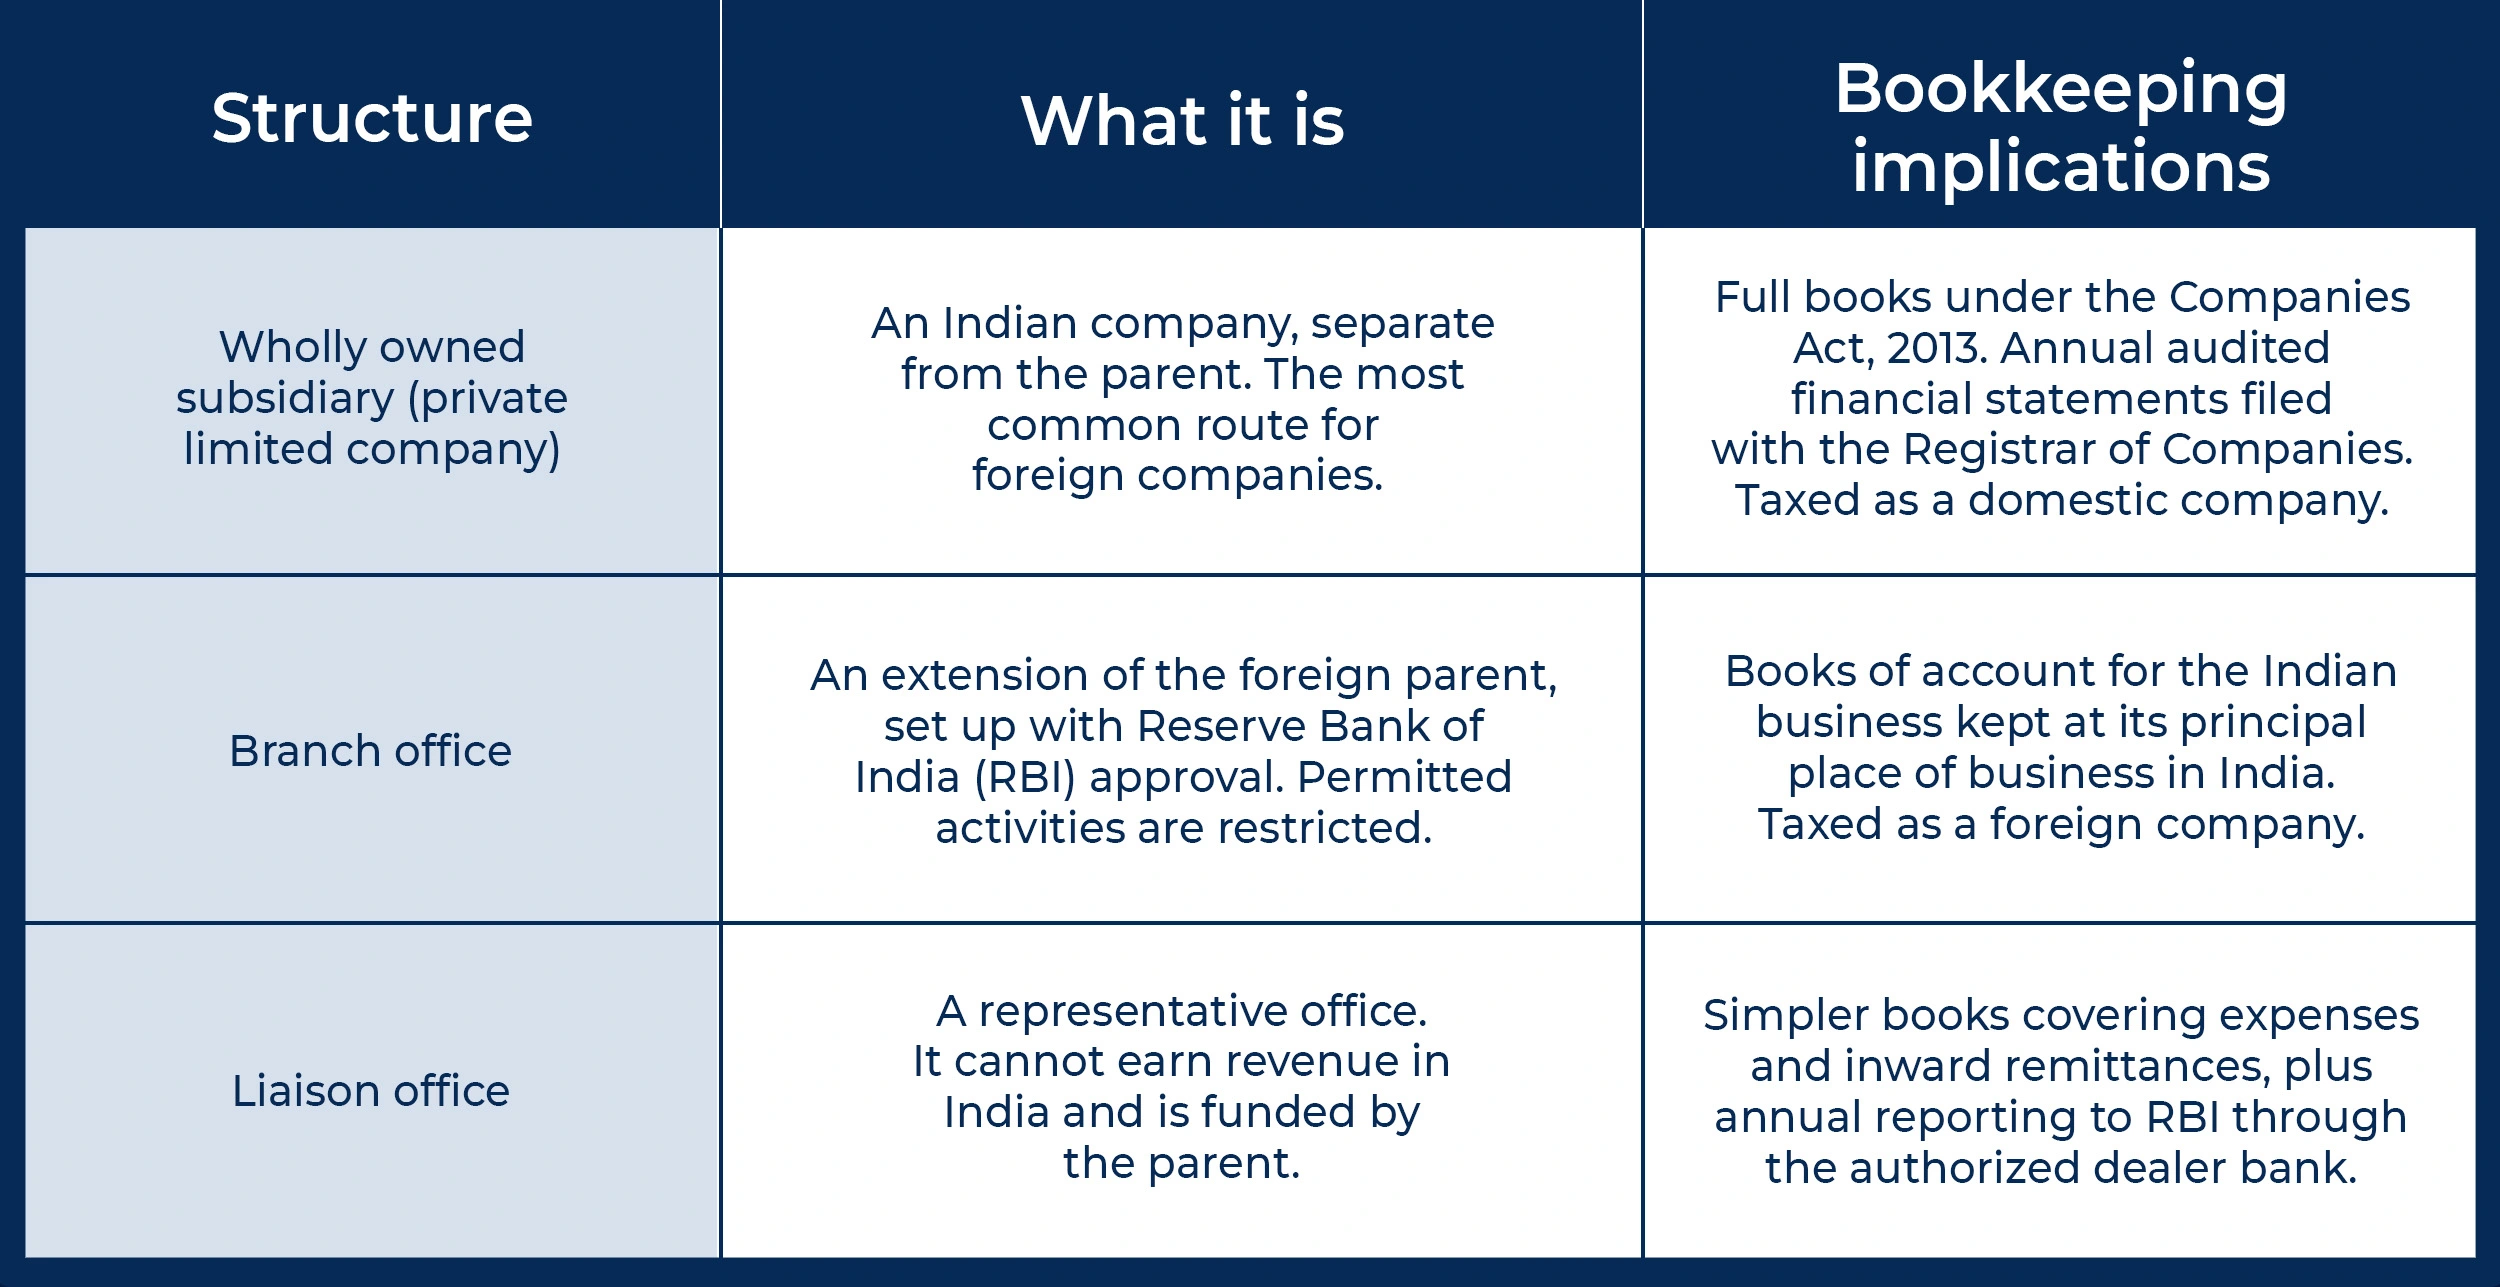
Most of this guide focuses on subsidiaries, since that is where the bulk of foreign investment and compliance activity sits.
1. The financial year runs April to March
Indian companies must use a financial year ending 31 March. A subsidiary of a foreign company can apply to the National Company Law Tribunal to align its statutory year with the parent's for consolidation purposes.
The tax year, however, stays April to March for everyone. A calendar-year group will therefore run at least two closes for India: a 31 March close for tax and a 31 December close for group reporting. Build both into the calendar from the start.
2. Every company is audited
Every Indian company, whatever its size or turnover, must appoint a statutory auditor and file audited financial statements. This is a significant difference for US parents, whose private subsidiaries often have no audit requirement, and for European groups used to small-company audit exemptions.
A separate tax audit applies once turnover crosses prescribed thresholds. Audit-ready books are not a nice-to-have in India. They are the baseline.
3. Your books must stay accessible in India
Books of account must be kept at the registered office in India (or another location in India approved by the board and notified to the Registrar). Electronic books are permitted, but they must remain accessible in India at all times, and a backup must be kept daily on servers physically located in India.
This matters for groups running a global ERP hosted in the US or Europe. The primary system can sit abroad, but the India backup is not optional. Confirm the arrangement with your ERP provider before go-live.
4. Your accounting software needs a permanent audit trail
Since financial years beginning 1 April 2023, Indian companies must use accounting software that records an audit trail of every transaction, with an edit log of each change and the date it was made. The audit trail cannot be capable of being disabled, and statutory auditors report on compliance.
Many global ERP and cloud accounting tools support this, but it is often a configuration choice rather than a default. Test it for your Indian entity before the first transaction is posted.
5. Indian GAAP, not IFRS, for most new subsidiaries
India has two accounting frameworks. Ind AS is converged with IFRS and applies to listed companies, unlisted companies with net worth of INR 2.5 billion (INR 250 crore) or more, and their group companies. Most new subsidiaries fall below these thresholds and report under Indian GAAP (the Accounting Standards notified under the Companies Act).
In practice, this means maintaining a reconciliation between Indian statutory accounts and the group's US GAAP or IFRS reporting. Agree the mapping and the chart of accounts upfront, not at year-end.
6. Tax compliance runs on a monthly cycle
Two regimes drive most of the monthly workload:
• GST (Goods and Services Tax). Monthly or quarterly returns, depending on turnover, plus an annual return. Businesses with aggregate turnover of INR 50 million (INR 5 crore) or more must issue e-invoices for B2B supplies. Input tax credit depends on suppliers' filings matching yours, so supplier reconciliation is a monthly task.
• TDS (tax deducted at source). India's with holding regime is far broader than in the US or most of Europe. Tax is withheld on salaries, rent, professional and technical fees, contractor payments and most cross-border payments. Deductions are deposited monthly and reported quarterly.
Both need to be captured at the point of booking each invoice. Reconstructing GST and TDS data at quarter-end is the most common source of penalties and lost tax credits.
7. Intercompany transactions draw close scrutiny
Management fees, royalties, software charges, cost allocations, loans and the purchase or sale of goods with group companies are all international transactions under India's transfer pricing rules. They require arm's length pricing, contemporaneous documentation and an annual accountant's report.
Cross-border payments to the parent also carry withholding tax and foreign exchange (FEMA) reporting obligations. Companies with foreign investment file an annual Foreign Liabilities and Assets (FLA) return with the RBI. Record every intercompany transaction against a signed agreement and an invoice from day one.
Two reforms affect bookkeeping and payroll for any company operating in India today:
• Income-tax Act, 2025. In force from 1 April 2026, it replaces the Income-tax Act, 1961. It introduces a single "tax-year" concept in place of the old previous year and assessment year, and renumbers provisions and forms. Chart-of-accounts mappings, tax calendars and templates built under the old law need updating.
• The four Labour Codes. In force from 21 November 2025, they consolidate 29 central labor laws. Under the Code on Wages, excluded allowances above 50% of total pay are added back to "wages", which raises social security contributions and gratuity provisions for many salary structures. Payroll design and gratuity accruals should be reviewed.
A complete set of books for an Indian subsidiary typically covers:
• Sales invoices, credit notes and customer receipts
• Purchase invoices, expense claims and supporting documents
• Bank statements and monthly bank reconciliations
• Payroll registers, statutory contribution records and employee reimbursements
• GST and TDS working papers, challans and returns
• Fixed asset register
• Inter-company agreements, invoices and balance confirmations
• Board minutes and statutory registers
Books and supporting vouchers must be retained for at least eight years.
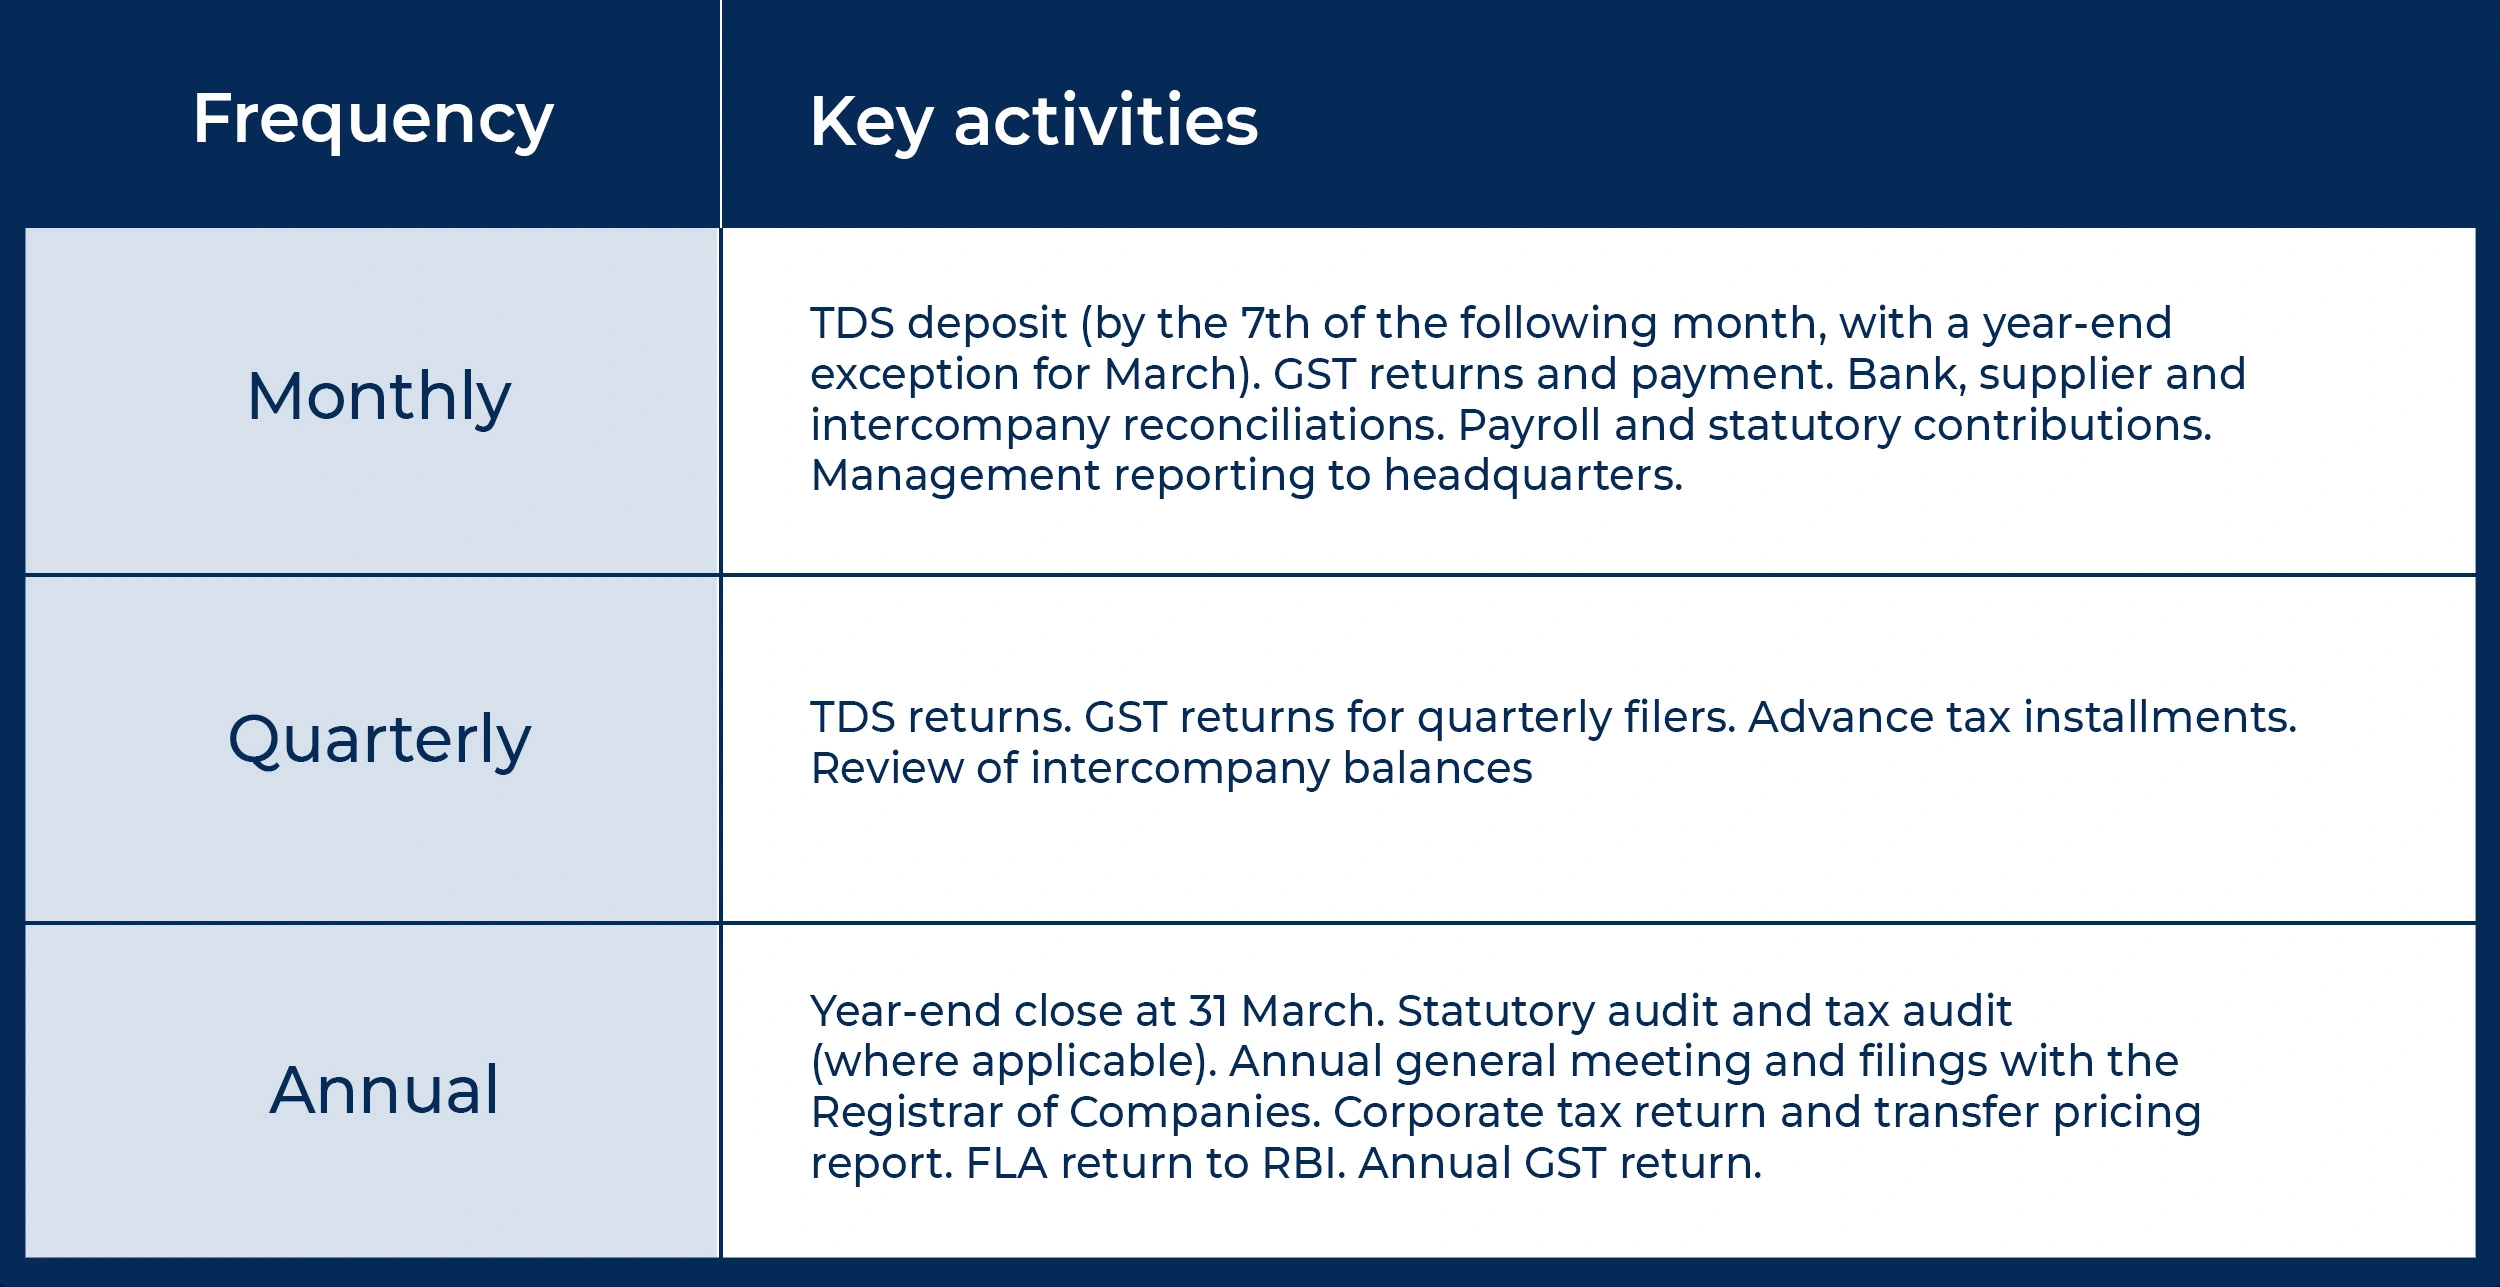
Exact due dates are set by notification and change from time to time. Maintain a compliance calendar that is reviewed against current notifications every quarter.
Most foreign companies start with an outsourced model and bring finance in-house as the Indian operation scales.
• Outsourced. An Indian provider maintains the books, runs payroll and tax compliance, and delivers a monthly reporting pack. This suits early-stage entities with low transaction volumes and no local finance hire yet.
• Hybrid. A local finance manager or controller owns the numbers, with external support for tax, payroll and statutory filings. This is the most common model for subsidiaries with an operating business in India.
• In-house. A full finance team, typically once transaction volumes, headcount and reporting demands justify it.
Whichever model you choose, keep four controls with the parent: approval of payments above a set limit, bank signatory rights, a monthly reporting pack in group format, and a defined escalation route for tax and regulatory notices.
Before the first invoice is raised in India, confirm that you have:
• Chosen the entity structure and confirmed its bookkeeping obligations
• Decided the statutory financial year and the group reporting calendar
• Built an Indian chart of accounts mapped to the group chart of accounts
• Selected accounting software with a compliant audittrail and an India-located daily backup
• Registered for GST and obtained a tax deduction account number (TAN) for TDS
• Set up GST and TDS capture at the point of booking each transaction
• Signed inter company agreements and set transfer pricing policies
• Designed payroll under the Labour Codes wage structure
• Appointed a statutory auditor
• Agreed the monthly close timetable and reporting packfor headquarters
• Created a compliance calendar with named owners
Tecnova has supported more than2,000 global businesses in India over 40 years. We do not stop at advice. Weset up and run the operation with you, from incorporation to the monthly close.
For foreign companies, our support covers:
• Company incorporation and the structure decision that shapes your compliance obligations
• Bookkeeping and accounting for your Indian entity, with reporting packs in your group format
• Corporate secretarial support for boardprocesses, statutory registers and filings with the Registrar of Companies
• PEO, EOR and incubation options for companies that want to hire and operate before setting up an entity
The objective is simple: books that pass an Indian audit and numbers your headquarters can rely on. That is what we mean by Making India Easy.
Planning to set up or scalein India? Speak to our team at enquiries@tecnovaglobal.com.
➣ Do foreign companies have to keep books of account in India?
Yes. An Indian subsidiary must keep books at its registered office in India. A foreign company operating through a branch must keep books for its Indian business at its principal place of business in India. Electronic books are permitted, with a daily backup on servers located in India.
➣ Can an Indian sub-sidiary follow the parent's calendar year?
For statutory reporting, a subsidiary of a foreign company can apply to the National Company Law Tribunal to adopt a different financial year for consolidation. For tax, the year runs April to March for every company.
➣ Does an Indian subsidiary report under IFRS?
Usually not. Ind AS, which is converged with IFRS, applies to listed companies, unlisted companies with net worth of INR 2.5 billion or more, and their group companies. Most new-subsidiaries report under Indian GAAP and reconcile to the group's US GAAP or IFRS accounts.
➣ Is an audit mandatory for a small Indian subsidiary?
Yes. Every company incorporatedin India must have its financial statements audited by a statutory auditor,regardless of size. A tax audit applies in addition once turnover exceedsprescribed thresholds.
➣ How long must records be kept in India?
Books of account and supporting vouchers must be retained for at least eight years.
➣ Can a foreign company outsource bookkeeping in India?
Yes. Outsourcing is common, particularly in the first years of operation. Responsibility for the accuracy of the books stays with the company's directors, so the parent should retain approval rights, bank controls and a monthly reporting pack.
➣ What does bookkeeping cost for a foreign company in India?
It depends on transaction volume, head count, entity structure, the number of tax registrations and the group's reporting requirements. A useful starting point is to define the monthly reporting pack and compliance calendar first, then scope the support needed to deliver them.
What should US and European companies know about bookkeeping in India?
Why bookkeeping and accounting compliance in India differ from the US and Europe
How India's financial year and statutory audit requirements affect foreign companies
What are the key accounting requirements for foreign companies operating in India?
What are the key bookkeeping challenges foreign companies face in India?
How does India's tax and regulatory framework affect accounting operations?
What bookkeeping obligations apply to different India entry structures?
How can foreign companies establish an effective bookkeeping and accounting system in India?
Should foreign companies outsource bookkeeping in India or build an in-house finance team?
What records and compliance activities should foreign companies manage in India?
How Tecnova supports bookkeeping and accounting compliance for foreign companies in India
India is now one of the largest destinations for foreign investment. Total FDI inflows reached USD 94.5 billion in FY- 2025-26, the highest annual figure on record, according to recent data.
Most companies that set up in India plan the market strategy carefully. The surprises tend to come later, in the back office. India's financial year runs April to March. Every company is audited, regardless of size. Electronic books must be backed up daily on servers in India. Tax is withheld and deposited monthly, on payments most US and European companies would never withhold on.
None of this is difficult once it is designed in from day one. It becomes expensive when it is discovered at the first audit. This guide sets out what works differently in India and how to build a bookkeeping process that satisfies Indian regulators and your group reporting at the same time.
Key takeaways
• Your entity structure (subsidiary, branch or liaison office) determines your bookkeeping obligations.
• India's statutory and tax year runs April to March. Calendar-year groups usually run two closes.
• Every Indian company needs a statutory audit. There is no small-company exemption.
• Electronic books must stay accessible in India, with a daily backup on servers located in India.
• Most new subsidiaries report under Indian GAAP, not IFRS, so plan a GAAP bridge for consolidation.
• GST and with holding tax (TDS) run on monthly cycles and must be captured at transaction level.
Foreign companies typically operate in India through one of three structures. Each carries different bookkeeping obligations.
Most of this guide focuses on subsidiaries, since that is where the bulk of foreign investment and compliance activity sits.
1. The financial year runs April to March
Indian companies must use a financial year ending 31 March. A subsidiary of a foreign company can apply to the National Company Law Tribunal to align its statutory year with the parent's for consolidation purposes.
The tax year, however, stays April to March for everyone. A calendar-year group will therefore run at least two closes for India: a 31 March close for tax and a 31 December close for group reporting. Build both into the calendar from the start.
2. Every company is audited
Every Indian company, whatever its size or turnover, must appoint a statutory auditor and file audited financial statements. This is a significant difference for US parents, whose private subsidiaries often have no audit requirement, and for European groups used to small-company audit exemptions.
A separate tax audit applies once turnover crosses prescribed thresholds. Audit-ready books are not a nice-to-have in India. They are the baseline.
3. Your books must stay accessible in India
Books of account must be kept at the registered office in India (or another location in India approved by the board and notified to the Registrar). Electronic books are permitted, but they must remain accessible in India at all times, and a backup must be kept daily on servers physically located in India.
This matters for groups running a global ERP hosted in the US or Europe. The primary system can sit abroad, but the India backup is not optional. Confirm the arrangement with your ERP provider before go-live.
4. Your accounting software needs a permanent audit trail
Since financial years beginning 1 April 2023, Indian companies must use accounting software that records an audit trail of every transaction, with an edit log of each change and the date it was made. The audit trail cannot be capable of being disabled, and statutory auditors report on compliance.
Many global ERP and cloud accounting tools support this, but it is often a configuration choice rather than a default. Test it for your Indian entity before the first transaction is posted.
5. Indian GAAP, not IFRS, for most new subsidiaries
India has two accounting frameworks. Ind AS is converged with IFRS and applies to listed companies, unlisted companies with net worth of INR 2.5 billion (INR 250 crore) or more, and their group companies. Most new subsidiaries fall below these thresholds and report under Indian GAAP (the Accounting Standards notified under the Companies Act).
In practice, this means maintaining a reconciliation between Indian statutory accounts and the group's US GAAP or IFRS reporting. Agree the mapping and the chart of accounts upfront, not at year-end.
6. Tax compliance runs on a monthly cycle
Two regimes drive most of the monthly workload:
• GST (Goods and Services Tax). Monthly or quarterly returns, depending on turnover, plus an annual return. Businesses with aggregate turnover of INR 50 million (INR 5 crore) or more must issue e-invoices for B2B supplies. Input tax credit depends on suppliers' filings matching yours, so supplier reconciliation is a monthly task.
• TDS (tax deducted at source). India's with holding regime is far broader than in the US or most of Europe. Tax is withheld on salaries, rent, professional and technical fees, contractor payments and most cross-border payments. Deductions are deposited monthly and reported quarterly.
Both need to be captured at the point of booking each invoice. Reconstructing GST and TDS data at quarter-end is the most common source of penalties and lost tax credits.
7. Intercompany transactions draw close scrutiny
Management fees, royalties, software charges, cost allocations, loans and the purchase or sale of goods with group companies are all international transactions under India's transfer pricing rules. They require arm's length pricing, contemporaneous documentation and an annual accountant's report.
Cross-border payments to the parent also carry withholding tax and foreign exchange (FEMA) reporting obligations. Companies with foreign investment file an annual Foreign Liabilities and Assets (FLA) return with the RBI. Record every intercompany transaction against a signed agreement and an invoice from day one.
Two reforms affect bookkeeping and payroll for any company operating in India today:
• Income-tax Act, 2025. In force from 1 April 2026, it replaces the Income-tax Act, 1961. It introduces a single "tax-year" concept in place of the old previous year and assessment year, and renumbers provisions and forms. Chart-of-accounts mappings, tax calendars and templates built under the old law need updating.
• The four Labour Codes. In force from 21 November 2025, they consolidate 29 central labor laws. Under the Code on Wages, excluded allowances above 50% of total pay are added back to "wages", which raises social security contributions and gratuity provisions for many salary structures. Payroll design and gratuity accruals should be reviewed.
A complete set of books for an Indian subsidiary typically covers:
• Sales invoices, credit notes and customer receipts
• Purchase invoices, expense claims and supporting documents
• Bank statements and monthly bank reconciliations
• Payroll registers, statutory contribution records and employee reimbursements
• GST and TDS working papers, challans and returns
• Fixed asset register
• Inter-company agreements, invoices and balance confirmations
• Board minutes and statutory registers
Books and supporting vouchers must be retained for at least eight years.
Exact due dates are set by notification and change from time to time. Maintain a compliance calendar that is reviewed against current notifications every quarter.
Most foreign companies start with an outsourced model and bring finance in-house as the Indian operation scales.
• Outsourced. An Indian provider maintains the books, runs payroll and tax compliance, and delivers a monthly reporting pack. This suits early-stage entities with low transaction volumes and no local finance hire yet.
• Hybrid. A local finance manager or controller owns the numbers, with external support for tax, payroll and statutory filings. This is the most common model for subsidiaries with an operating business in India.
• In-house. A full finance team, typically once transaction volumes, headcount and reporting demands justify it.
Whichever model you choose, keep four controls with the parent: approval of payments above a set limit, bank signatory rights, a monthly reporting pack in group format, and a defined escalation route for tax and regulatory notices.
Before the first invoice is raised in India, confirm that you have:
• Chosen the entity structure and confirmed its bookkeeping obligations
• Decided the statutory financial year and the group reporting calendar
• Built an Indian chart of accounts mapped to the group chart of accounts
• Selected accounting software with a compliant audittrail and an India-located daily backup
• Registered for GST and obtained a tax deduction account number (TAN) for TDS
• Set up GST and TDS capture at the point of booking each transaction
• Signed inter company agreements and set transfer pricing policies
• Designed payroll under the Labour Codes wage structure
• Appointed a statutory auditor
• Agreed the monthly close timetable and reporting packfor headquarters
• Created a compliance calendar with named owners
Tecnova has supported more than2,000 global businesses in India over 40 years. We do not stop at advice. Weset up and run the operation with you, from incorporation to the monthly close.
For foreign companies, our support covers:
• Company incorporation and the structure decision that shapes your compliance obligations
• Bookkeeping and accounting for your Indian entity, with reporting packs in your group format
• Corporate secretarial support for boardprocesses, statutory registers and filings with the Registrar of Companies
• PEO, EOR and incubation options for companies that want to hire and operate before setting up an entity
The objective is simple: books that pass an Indian audit and numbers your headquarters can rely on. That is what we mean by Making India Easy.
Planning to set up or scalein India? Speak to our team at enquiries@tecnovaglobal.com.
➣ Do foreign companies have to keep books of account in India?
Yes. An Indian subsidiary must keep books at its registered office in India. A foreign company operating through a branch must keep books for its Indian business at its principal place of business in India. Electronic books are permitted, with a daily backup on servers located in India.
➣ Can an Indian sub-sidiary follow the parent's calendar year?
For statutory reporting, a subsidiary of a foreign company can apply to the National Company Law Tribunal to adopt a different financial year for consolidation. For tax, the year runs April to March for every company.
➣ Does an Indian subsidiary report under IFRS?
Usually not. Ind AS, which is converged with IFRS, applies to listed companies, unlisted companies with net worth of INR 2.5 billion or more, and their group companies. Most new-subsidiaries report under Indian GAAP and reconcile to the group's US GAAP or IFRS accounts.
➣ Is an audit mandatory for a small Indian subsidiary?
Yes. Every company incorporatedin India must have its financial statements audited by a statutory auditor,regardless of size. A tax audit applies in addition once turnover exceedsprescribed thresholds.
➣ How long must records be kept in India?
Books of account and supporting vouchers must be retained for at least eight years.
➣ Can a foreign company outsource bookkeeping in India?
Yes. Outsourcing is common, particularly in the first years of operation. Responsibility for the accuracy of the books stays with the company's directors, so the parent should retain approval rights, bank controls and a monthly reporting pack.
➣ What does bookkeeping cost for a foreign company in India?
It depends on transaction volume, head count, entity structure, the number of tax registrations and the group's reporting requirements. A useful starting point is to define the monthly reporting pack and compliance calendar first, then scope the support needed to deliver them.