Services


Sectors
Insights
COMMERCIALIZATION
Insights



Follow Us

Key highlights: Polyethylene market entry in India
Polyethylene market entry in India offers foreign companies access to one of the world's largest polymer-consuming economies. Polyethylene supports several industries across India, such as pharmaceutical packaging, agricultural films, automotive components, etc.
The opportunity in India is supported by growing domestic demand, expanding manufacturing capabilities and growing infrastructure investments. Reports suggest that India's polyethylene demand grew at an annual rate of 7% between FY- 2017-18 and FY- 2025-26.
However, if a foreign company wants to enter this market, they need to understand product standards, import regulations, environmental obligations and local sourcing dynamics to establish a sustainable presence.
India presents substantial opportunities for foreign polyethylene manufacturers, suppliers and investors. The country's expanding industrial base creates demand for different polyethylene grades. These include HDPE, LDPE and LLDPE.
According to industry reports, India's HDPE market valuation is USD 3.39 billion in 2026. It is projected to reach USD 4.70 billion by 2034, with a CAGR of 4.18% between 2026 and 2034.
Several factors such as infrastructure development, packaging demand and agricultural modernization work as key growth drivers.
The nation permits 100% FDI under the automatic routein the manufacturing sector. However, it is subject to applicable regulations.This also creates opportunities for foreign businesses who prefer contractmanufacturing to a fully owned production facility.
Before deciding how to enter India’s polyethylene market, foreign companies should evaluate:
India's polyethylene demand continues to benefit from industrial expansion and changing consumption patterns. Reports show that India produced around 3046.1 MT of LLDPE, 1856.2 MT of HDPE and 617.4 MT of LDPE in FY- 2024-25.
Here is adetailed understanding of three important sectors which offer clearopportunities for foreign businesses:
1. Increasing use in automotive manufacturing: India's automotive industry creates demand for lightweight, durable and cost-effective polymer components. Polyethylene is used in fuel tanks, protective films, cable insulation, fluid containers and other selected interior applications. Foreign suppliers can target automotive component manufacturers. They can target suppliers who need consistent quality, technical support and reliable supply. Specialized grades can also help businesses differentiate themselves from suppliers of standard polyethylene products.
2. Increasing use in pharmaceutical packaging: Pharmaceutical packaging is another important demand segment in India. HDPE and LDPE are widely used in bottles, flexible packaging and protective applications. India's pharmaceutical manufacturing sector serves both domestic and international markets. This creates demand for packaging materials that meet strict quality and safety requirements.
If you are a foreign polyethylene supplier, you canexplore opportunities in medical-grade and pharmaceutical packagingapplications as well. However, you need to keep in mind that you need to verifythe material specifications and applicable regulatory requirements for each enduse.
3. Growing adoption in Agriculture: Agriculture offers significant opportunities for polyethylene products. Farmers and agricultural businesses use polyethylene films, irrigation pipes, greenhouse covers, water storage solutions and protective packaging.
This segment offers opportunities for foreign businesses. They can explore opportunities in agricultural equipment manufacturers, irrigation solution providers and local polymer converters.

Foreign companies need to comply with India's product quality, import, packaging and environmental regulations. Here is a detailed understanding of the key compliances for foreign companies selling PE products in India:
1. Quality norms and product standards: The Bureau of Indian Standards (BIS) governs several product quality requirements in India. Foreign manufacturers must check whether their polyethylene products fall under a compulsory Quality Control Order (QCO).
The Department of Chemicals and Petrochemicals issuedan amendment to the Polyethylene Material for Molding and Extrusion QualityControl Order in June 2025. As a business owner, you need to keep in mind thatnot every polyethylene grade follows identical certification requirements.Product classification is an important factor here.
2. Regulations in labelling and packaging: India's Legal Metrology (Packaged Commodities) Rules,2011 govern declarations on applicable pre-packaged commodities. You must assess requirements such as product identity, manufacturer or importer details, quantity and country of origin. Applicable declarations may differ based on packaging type and intended market. Plastic packaging also falls under the Plastic Waste Management Rules, 2016. Their Extended Producer Responsibility (EPR) framework places obligations on producers, importers and brand owners.
3. Compliance with imports and customs: An Importer Exporter Code (IEC) is generally mandatory for import and export activities. The Directorate General of Foreign Trade issues this code. This code is linked to the entity's Permanent Account Number(PAN). Customs duties can influence the landed cost of imported polyethylene. Therefore, businesses must evaluate the applicable tariff classification before they finalize their pricing strategy.
4. Taxes and regulatory filings: Foreign businesses must understand India's tax and corporate compliance frame work before starting their operations. The Goods and Services Tax (GST) applies to taxable supplies of polyethylene products. The applicable rate depends on the product's classification and current tax notifications. Importers must also account for customs duties and applicable import-related taxes. Their financial model should reflect the total land cost rather than the overseas product price alone.
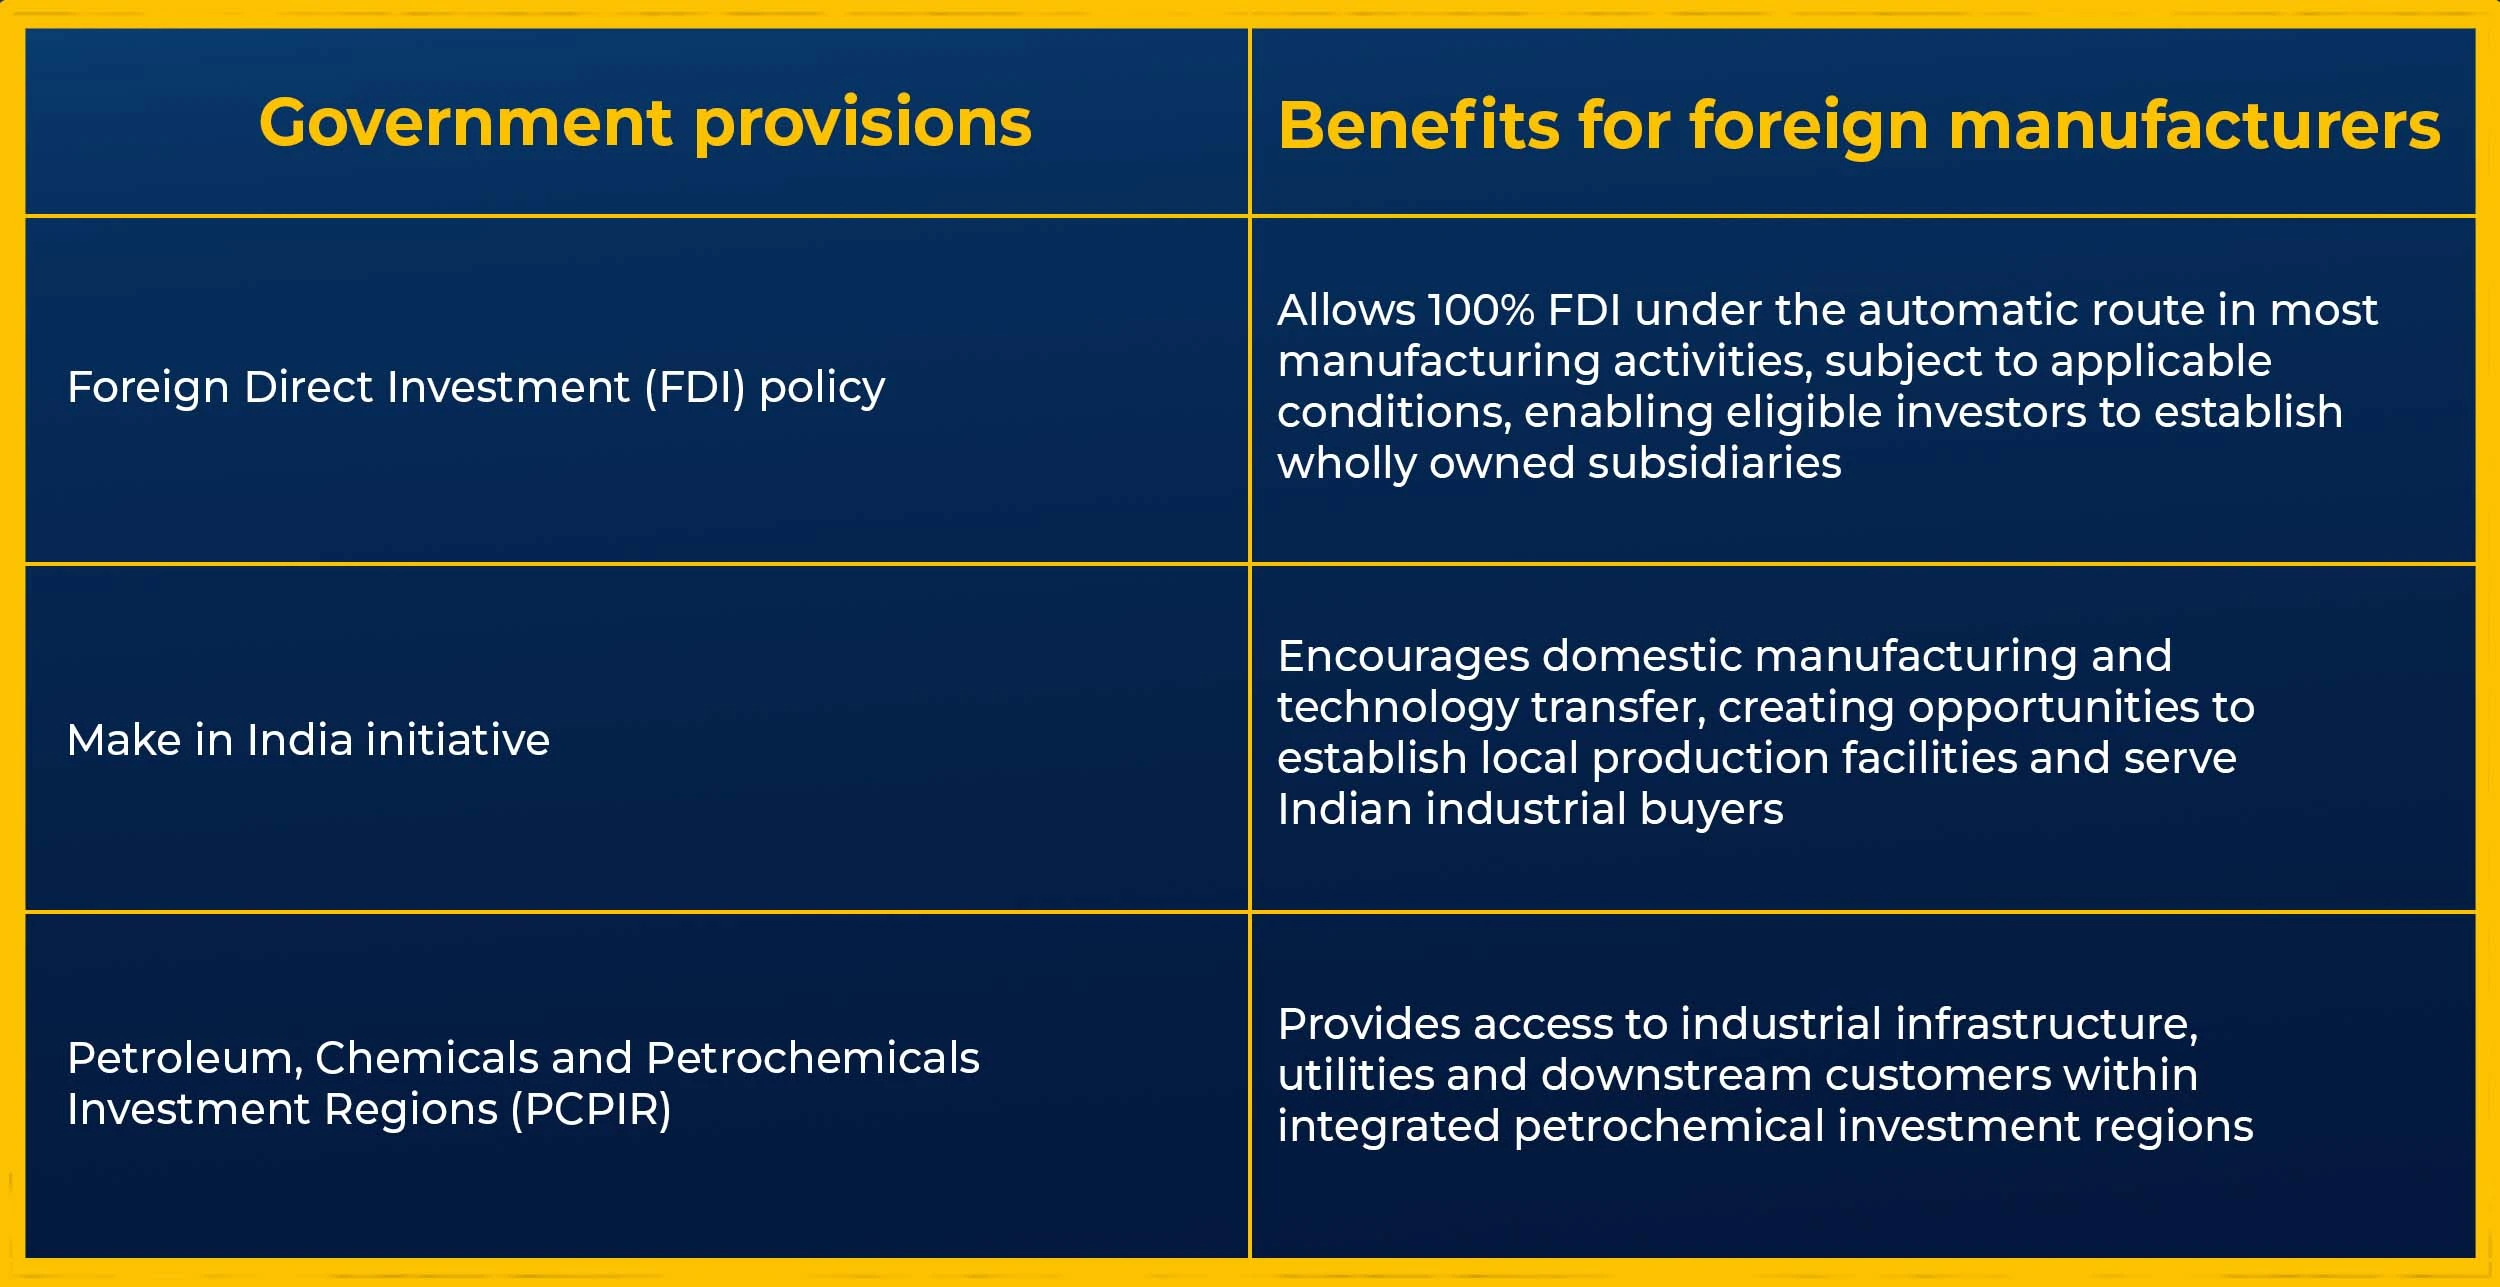
The Indian government has introduced several policies to strengthen domestic manufacturing, attract foreign investment and improve industrial infrastructure. Here is a detailed understanding of which government policies support foreign businesses' polyethylene market entry in India:
For foreign manufacturers, polyethylene market entryin India requires a clear understanding of the country’s industrial landscape,regulatory framework and demand across target sectors. Tecnova supportsbusinesses in evaluating market opportunities, developing suitable entrystrategies and planning local operations. Our services include:
1. Why should global chemical leaders look at India over other expansion hubs right now?
Most markets force a trade-off. Established industrial hubs in Europe and East Asia offer mature supply chains but face slowing domestic demand, while parts of Southeast Asia or the GCC are oriented primarily toward raw feedstock production or export processing.
India brings both sides together: structural, grade-specific supply deficits combined with massive, non-cyclical internal consumption. Its chemical and petrochemical market is on track toward USD 300billion by 2028 and projected to reach USD 1 trillion by 2040. Backed by nationwide infrastructure upgrades, city gas expansion, automotive light-weighting and retail packaging, polymer consumption is sustaining a steady ~7% annual growth rate-giving global suppliers a reliable volume hedge against slower domestic markets.
2. Local refiners have huge capacity. Where can an international supplier compete profitably?
India's domestic producers operate world-scale facilities, but their output is heavily focused on standard, high-volume commodity grades (like standard C4 film and general injection molding). That leaves major gaps in specialized, high-performance formulations where local converters are forced to rely on imports:
Metallocene PE (mLLDPE / mHDPE): Essential for high-speed form-fill-seal (FFS) packaging, stretch wraps and puncture-resistant agricultural greenhouse films
Specialized HDPE: Certified PE-80 and PE-100 pressure pipe resins for water grids, as well as high-molecular-weight grades (HMW-HDPE) used for UN-rated chemical drums.
Autoclave & Tubular LDPE: A structural domestic shortfall persists for high-speed extrusion coating, aseptic beverage cartons and pharmaceutical-grade containers.
If your portfolio focuses on tight specifications, specialized melt-flow characteristics, or high-barrier performance, you aren't competing with local commodity pricing—you are filling an urgent domestic supply gap.
3. What is the ground reality with the Bureau of Indian Standards (BIS) Quality Control Orders?
BIS compliance is non-negotiable and often becomes a major bottleneck if treated as an afterthought. Under mandatory Quality Control Orders (such as IS7328 for HDPE and IS 6192 for LDPE/LLDPE), foreign manufacturers must secure certification under the Foreign Manufacturers Certification Scheme (FMCS)before their resin can legally enter an Indian port.
This process involves official plant audits of overseas manufacturing sites by Indian inspectors and extensive testing at certified domestic labs, typically requiring 6 to 9 months. Navigating grade-specific exemptions (such as metallocene formulations) and aligning 8-digit HS codes under Chapter 3901 early on is essential to prevent costly demurrage and cargo holds at ports like Nhava Sheva or Mundra.
4. Can foreign companies own 100% of their operations in India?
Yes. India permits 100% Foreign Direct Investment (FDI) under the automatic route for chemical and polymer manufacturing. This means
5. How can overseas suppliers match domestic delivery speeds when ocean freight takes 30–45 days?
To compete with local plants capable of dispatching resin by road within48 hours, global suppliers typically utilize Free Trade Warehousing Zones(FTWZs) located near major industrial belts (such as Panvel near Mumbai or Sri City near Chennai). Operating through an FTWZ allows you to store bulk inventory on Indian soil under a duty-deferred model. You retain title and transact in foreign currency, while Basic Customs Duty (BCD) and Integrated GST (IGST) are only paid when the local converter places an order and clears the lot for domestic use. This reduces turnaround time from several weeks to 48–72 hours, matching domestic responsiveness without tying up upfront tax capital.
6. What operational advantages do Petroleum, Chemicals and Petrochemicals Investment Regions (PCPIRs) offer?
Setting up outside dedicated chemical infrastructure in India can lead to significant delays in environmental permitting and utility connections. India’s dedicated PCPIR corridors—notably at Dahej (Gujarat), Paradeep(Odisha) and Kakinada (Andhra Pradesh)- are engineered to solve these operational hurdles:
7. How does Extended Producer Responsibility (EPR) affect foreign resin suppliers?
Under India’s Plastic Waste Management (PWM) Rules, foreign producers and importers cannot treat resin supply as a simple drop-ship transaction. Entities introducing virgin plastic into the Indian market are classified as Producers, Importers and Brand Owners (PIBOs).
This requires mandatory registration on the Central Pollution Control Board (CPCB) portal, end-to-end supply chain traceability and the procurement of verifiable recycling credits to offset statutory plastic recovery obligations. Ensuring this compliance setup is operational before dispatching commercial volumes prevents port delays and regulatory penalties.
8. What is the most practical step-by-step entry path for an international polymer company?
Most global chemical firms scale their footprint in stages to manage financial risk and validate margins:
9. What should we anticipate regarding import duties, trade agreements and trade defence measures?
Polyethylene imports are subject to a standard Basic Customs Duty (BCD)of ~7.5% under Chapter 3901, along with an 18% Integrated GST (which functions as a pass-through Input Tax Credit for registered Indian converters). However, trade agreements can shift these economics significantly. Shipments routed through countries with active Free Trade Agreements (such as the India-UAE CEPA or India-Singapore CECA) can often access preferential duty rates. At the same time, companies must monitor trade defense actions: the Directorate General of Trade Remedies (DGTR) routinely evaluates anti-dumping petitions on select polymer grades to safeguard domestic margins against regional spot surpluses.
10. How does Tecnova de-risk the market entry process for executive leadership teams?
Entering the Indian chemical sector involves navigating multiple regulatory layers, state-level land acquisition rules and a fragmented converter base. Tecnova acts as an executive extension on the ground, helping international leadership teams make informed, risk-adjusted decisions:
List of Abbreviations
FMCS- Foreign Manufacturers Certification Scheme
FTA-Free Trade Agreement
HDPE-High-Density Polyethylene
IPP-Import Parity Pricing
LDPE-Low-Density Polyethylene
LLDPE-Linear Low-Density Polyethylene
mPE-Metallocene Polyethylene
PCPIR-Petroleum, Chemicals and Petrochemical Investment Region
PCR-Post-Consumer Recyclate
QCO-Quality Control Order
SUP-Single-Use Plastics
Key highlights: Polyethylene market entry in India
Polyethylene market entry in India offers foreign companies access to one of the world's largest polymer-consuming economies. Polyethylene supports several industries across India, such as pharmaceutical packaging, agricultural films, automotive components, etc.
The opportunity in India is supported by growing domestic demand, expanding manufacturing capabilities and growing infrastructure investments. Reports suggest that India's polyethylene demand grew at an annual rate of 7% between FY- 2017-18 and FY- 2025-26.
However, if a foreign company wants to enter this market, they need to understand product standards, import regulations, environmental obligations and local sourcing dynamics to establish a sustainable presence.
India presents substantial opportunities for foreign polyethylene manufacturers, suppliers and investors. The country's expanding industrial base creates demand for different polyethylene grades. These include HDPE, LDPE and LLDPE.
According to industry reports, India's HDPE market valuation is USD 3.39 billion in 2026. It is projected to reach USD 4.70 billion by 2034, with a CAGR of 4.18% between 2026 and 2034.
Several factors such as infrastructure development, packaging demand and agricultural modernization work as key growth drivers.
The nation permits 100% FDI under the automatic routein the manufacturing sector. However, it is subject to applicable regulations.This also creates opportunities for foreign businesses who prefer contractmanufacturing to a fully owned production facility.
Before deciding how to enter India’s polyethylene market, foreign companies should evaluate:
India's polyethylene demand continues to benefit from industrial expansion and changing consumption patterns. Reports show that India produced around 3046.1 MT of LLDPE, 1856.2 MT of HDPE and 617.4 MT of LDPE in FY- 2024-25.
Here is adetailed understanding of three important sectors which offer clearopportunities for foreign businesses:
1. Increasing use in automotive manufacturing: India's automotive industry creates demand for lightweight, durable and cost-effective polymer components. Polyethylene is used in fuel tanks, protective films, cable insulation, fluid containers and other selected interior applications. Foreign suppliers can target automotive component manufacturers. They can target suppliers who need consistent quality, technical support and reliable supply. Specialized grades can also help businesses differentiate themselves from suppliers of standard polyethylene products.
2. Increasing use in pharmaceutical packaging: Pharmaceutical packaging is another important demand segment in India. HDPE and LDPE are widely used in bottles, flexible packaging and protective applications. India's pharmaceutical manufacturing sector serves both domestic and international markets. This creates demand for packaging materials that meet strict quality and safety requirements.
If you are a foreign polyethylene supplier, you canexplore opportunities in medical-grade and pharmaceutical packagingapplications as well. However, you need to keep in mind that you need to verifythe material specifications and applicable regulatory requirements for each enduse.
3. Growing adoption in Agriculture: Agriculture offers significant opportunities for polyethylene products. Farmers and agricultural businesses use polyethylene films, irrigation pipes, greenhouse covers, water storage solutions and protective packaging.
This segment offers opportunities for foreign businesses. They can explore opportunities in agricultural equipment manufacturers, irrigation solution providers and local polymer converters.
Foreign companies need to comply with India's product quality, import, packaging and environmental regulations. Here is a detailed understanding of the key compliances for foreign companies selling PE products in India:
1. Quality norms and product standards: The Bureau of Indian Standards (BIS) governs several product quality requirements in India. Foreign manufacturers must check whether their polyethylene products fall under a compulsory Quality Control Order (QCO).
The Department of Chemicals and Petrochemicals issuedan amendment to the Polyethylene Material for Molding and Extrusion QualityControl Order in June 2025. As a business owner, you need to keep in mind thatnot every polyethylene grade follows identical certification requirements.Product classification is an important factor here.
2. Regulations in labelling and packaging: India's Legal Metrology (Packaged Commodities) Rules,2011 govern declarations on applicable pre-packaged commodities. You must assess requirements such as product identity, manufacturer or importer details, quantity and country of origin. Applicable declarations may differ based on packaging type and intended market. Plastic packaging also falls under the Plastic Waste Management Rules, 2016. Their Extended Producer Responsibility (EPR) framework places obligations on producers, importers and brand owners.
3. Compliance with imports and customs: An Importer Exporter Code (IEC) is generally mandatory for import and export activities. The Directorate General of Foreign Trade issues this code. This code is linked to the entity's Permanent Account Number(PAN). Customs duties can influence the landed cost of imported polyethylene. Therefore, businesses must evaluate the applicable tariff classification before they finalize their pricing strategy.
4. Taxes and regulatory filings: Foreign businesses must understand India's tax and corporate compliance frame work before starting their operations. The Goods and Services Tax (GST) applies to taxable supplies of polyethylene products. The applicable rate depends on the product's classification and current tax notifications. Importers must also account for customs duties and applicable import-related taxes. Their financial model should reflect the total land cost rather than the overseas product price alone.
The Indian government has introduced several policies to strengthen domestic manufacturing, attract foreign investment and improve industrial infrastructure. Here is a detailed understanding of which government policies support foreign businesses' polyethylene market entry in India:
For foreign manufacturers, polyethylene market entryin India requires a clear understanding of the country’s industrial landscape,regulatory framework and demand across target sectors. Tecnova supportsbusinesses in evaluating market opportunities, developing suitable entrystrategies and planning local operations. Our services include:
1. Why should global chemical leaders look at India over other expansion hubs right now?
Most markets force a trade-off. Established industrial hubs in Europe and East Asia offer mature supply chains but face slowing domestic demand, while parts of Southeast Asia or the GCC are oriented primarily toward raw feedstock production or export processing.
India brings both sides together: structural, grade-specific supply deficits combined with massive, non-cyclical internal consumption. Its chemical and petrochemical market is on track toward USD 300billion by 2028 and projected to reach USD 1 trillion by 2040. Backed by nationwide infrastructure upgrades, city gas expansion, automotive light-weighting and retail packaging, polymer consumption is sustaining a steady ~7% annual growth rate-giving global suppliers a reliable volume hedge against slower domestic markets.
2. Local refiners have huge capacity. Where can an international supplier compete profitably?
India's domestic producers operate world-scale facilities, but their output is heavily focused on standard, high-volume commodity grades (like standard C4 film and general injection molding). That leaves major gaps in specialized, high-performance formulations where local converters are forced to rely on imports:
Metallocene PE (mLLDPE / mHDPE): Essential for high-speed form-fill-seal (FFS) packaging, stretch wraps and puncture-resistant agricultural greenhouse films
Specialized HDPE: Certified PE-80 and PE-100 pressure pipe resins for water grids, as well as high-molecular-weight grades (HMW-HDPE) used for UN-rated chemical drums.
Autoclave & Tubular LDPE: A structural domestic shortfall persists for high-speed extrusion coating, aseptic beverage cartons and pharmaceutical-grade containers.
If your portfolio focuses on tight specifications, specialized melt-flow characteristics, or high-barrier performance, you aren't competing with local commodity pricing—you are filling an urgent domestic supply gap.
3. What is the ground reality with the Bureau of Indian Standards (BIS) Quality Control Orders?
BIS compliance is non-negotiable and often becomes a major bottleneck if treated as an afterthought. Under mandatory Quality Control Orders (such as IS7328 for HDPE and IS 6192 for LDPE/LLDPE), foreign manufacturers must secure certification under the Foreign Manufacturers Certification Scheme (FMCS)before their resin can legally enter an Indian port.
This process involves official plant audits of overseas manufacturing sites by Indian inspectors and extensive testing at certified domestic labs, typically requiring 6 to 9 months. Navigating grade-specific exemptions (such as metallocene formulations) and aligning 8-digit HS codes under Chapter 3901 early on is essential to prevent costly demurrage and cargo holds at ports like Nhava Sheva or Mundra.
4. Can foreign companies own 100% of their operations in India?
Yes. India permits 100% Foreign Direct Investment (FDI) under the automatic route for chemical and polymer manufacturing. This means
5. How can overseas suppliers match domestic delivery speeds when ocean freight takes 30–45 days?
To compete with local plants capable of dispatching resin by road within48 hours, global suppliers typically utilize Free Trade Warehousing Zones(FTWZs) located near major industrial belts (such as Panvel near Mumbai or Sri City near Chennai). Operating through an FTWZ allows you to store bulk inventory on Indian soil under a duty-deferred model. You retain title and transact in foreign currency, while Basic Customs Duty (BCD) and Integrated GST (IGST) are only paid when the local converter places an order and clears the lot for domestic use. This reduces turnaround time from several weeks to 48–72 hours, matching domestic responsiveness without tying up upfront tax capital.
6. What operational advantages do Petroleum, Chemicals and Petrochemicals Investment Regions (PCPIRs) offer?
Setting up outside dedicated chemical infrastructure in India can lead to significant delays in environmental permitting and utility connections. India’s dedicated PCPIR corridors—notably at Dahej (Gujarat), Paradeep(Odisha) and Kakinada (Andhra Pradesh)- are engineered to solve these operational hurdles:
7. How does Extended Producer Responsibility (EPR) affect foreign resin suppliers?
Under India’s Plastic Waste Management (PWM) Rules, foreign producers and importers cannot treat resin supply as a simple drop-ship transaction. Entities introducing virgin plastic into the Indian market are classified as Producers, Importers and Brand Owners (PIBOs).
This requires mandatory registration on the Central Pollution Control Board (CPCB) portal, end-to-end supply chain traceability and the procurement of verifiable recycling credits to offset statutory plastic recovery obligations. Ensuring this compliance setup is operational before dispatching commercial volumes prevents port delays and regulatory penalties.
8. What is the most practical step-by-step entry path for an international polymer company?
Most global chemical firms scale their footprint in stages to manage financial risk and validate margins:
9. What should we anticipate regarding import duties, trade agreements and trade defence measures?
Polyethylene imports are subject to a standard Basic Customs Duty (BCD)of ~7.5% under Chapter 3901, along with an 18% Integrated GST (which functions as a pass-through Input Tax Credit for registered Indian converters). However, trade agreements can shift these economics significantly. Shipments routed through countries with active Free Trade Agreements (such as the India-UAE CEPA or India-Singapore CECA) can often access preferential duty rates. At the same time, companies must monitor trade defense actions: the Directorate General of Trade Remedies (DGTR) routinely evaluates anti-dumping petitions on select polymer grades to safeguard domestic margins against regional spot surpluses.
10. How does Tecnova de-risk the market entry process for executive leadership teams?
Entering the Indian chemical sector involves navigating multiple regulatory layers, state-level land acquisition rules and a fragmented converter base. Tecnova acts as an executive extension on the ground, helping international leadership teams make informed, risk-adjusted decisions:
List of Abbreviations
FMCS- Foreign Manufacturers Certification Scheme
FTA-Free Trade Agreement
HDPE-High-Density Polyethylene
IPP-Import Parity Pricing
LDPE-Low-Density Polyethylene
LLDPE-Linear Low-Density Polyethylene
mPE-Metallocene Polyethylene
PCPIR-Petroleum, Chemicals and Petrochemical Investment Region
PCR-Post-Consumer Recyclate
QCO-Quality Control Order
SUP-Single-Use Plastics